Most buyers at Pardos Sakura fund part of their purchase with a home loan rather than paying the full ₹2.80 Cr* and above entirely upfront. This guide covers how home loan eligibility, down payment and EMIs typically work for an under-construction project like Pardos Sakura, Sector 90 Gurgaon.
This is general information to help you plan, not financial advice. Loan terms vary by bank and change over time, so confirm current rates and eligibility directly with your lender.
How much loan can you get
Banks and housing finance companies generally lend a percentage of the property's value, commonly in the 75-90% range, with the exact loan-to-value ratio depending on the loan amount, your income and the lender's internal policy. The remaining amount is your own contribution, paid directly as per the payment plan.
Eligibility factors banks typically check
- Income and employment type. Salaried applicants usually need recent salary slips and bank statements; self-employed applicants need income tax returns and business proof.
- Credit score and repayment history. A clean credit history improves both approval chances and the interest rate offered.
- Age and loan tenure. Younger applicants can generally opt for longer tenures, which lowers the EMI.
- Existing obligations. Other ongoing EMIs reduce the loan amount a bank will approve.
Documents usually required
- KYC: PAN, Aadhaar, address proof
- Income proof: salary slips/ITR, bank statements (typically last 6 months)
- Property documents: EOI/booking receipt, allotment letter, cost sheet, builder-buyer agreement
- Passport-size photographs and a duly filled loan application form
Exact document lists vary by bank; your relationship manager will confirm what's needed once you choose a unit.
How EMIs work on a construction-linked plan
Pardos Sakura is an under-construction project, so most buyers taking a loan use a construction-linked payment plan rather than paying the full amount at booking. In that case:
- The bank disburses the loan in parts, matching each instalment as it falls due.
- Until the full loan amount is disbursed, you typically pay pre-EMI, which is interest only on the amount already released.
- Once the loan is fully disbursed (usually near possession), full EMIs begin, covering both principal and interest.
This means your actual outgo is lower during construction than it will be after possession, which is worth factoring into your budget. See the Pardos Sakura price list and payment plan guide for how instalments are typically structured.
A note on RERA and loan disbursal
RERA registration for Pardos Sakura has been applied for with HRERA Gurugram and is currently awaited. Most banks require a project's RERA number before disbursing a home loan against it, so confirm the current RERA status with the Pardos sales team and your bank before finalising your loan application timeline.
Before you apply
Get a pre-approved loan sanction letter (an in-principle approval) before you finalise your unit — it gives you a clear budget and strengthens your negotiating position. Compare interest rates and processing fees across at least two or three lenders, since both vary by bank and by your profile.
Why buyers shortlist Pardos Sakura
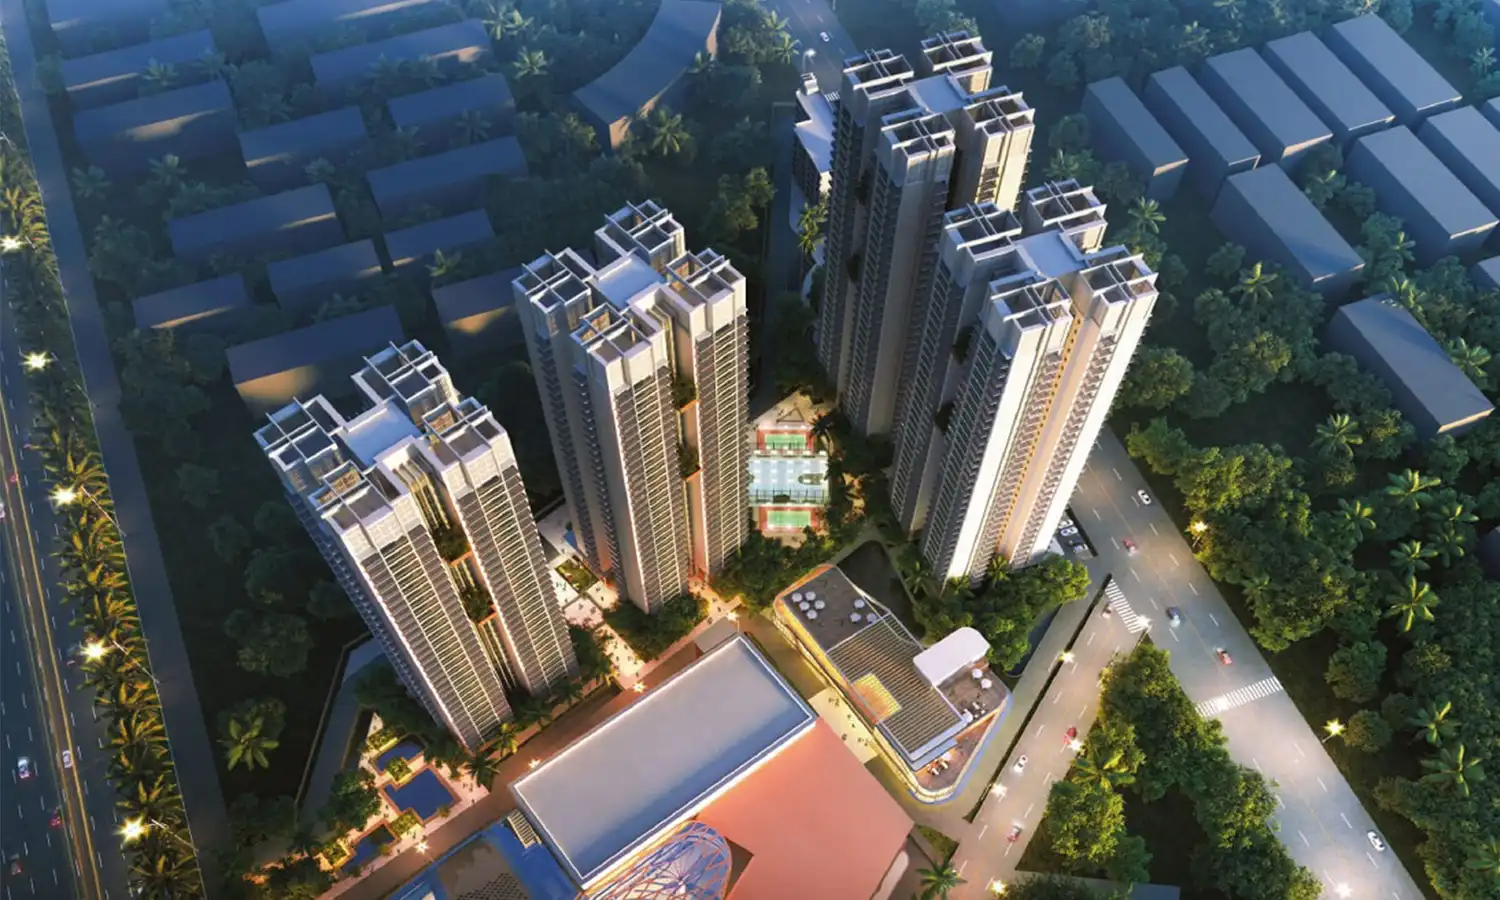
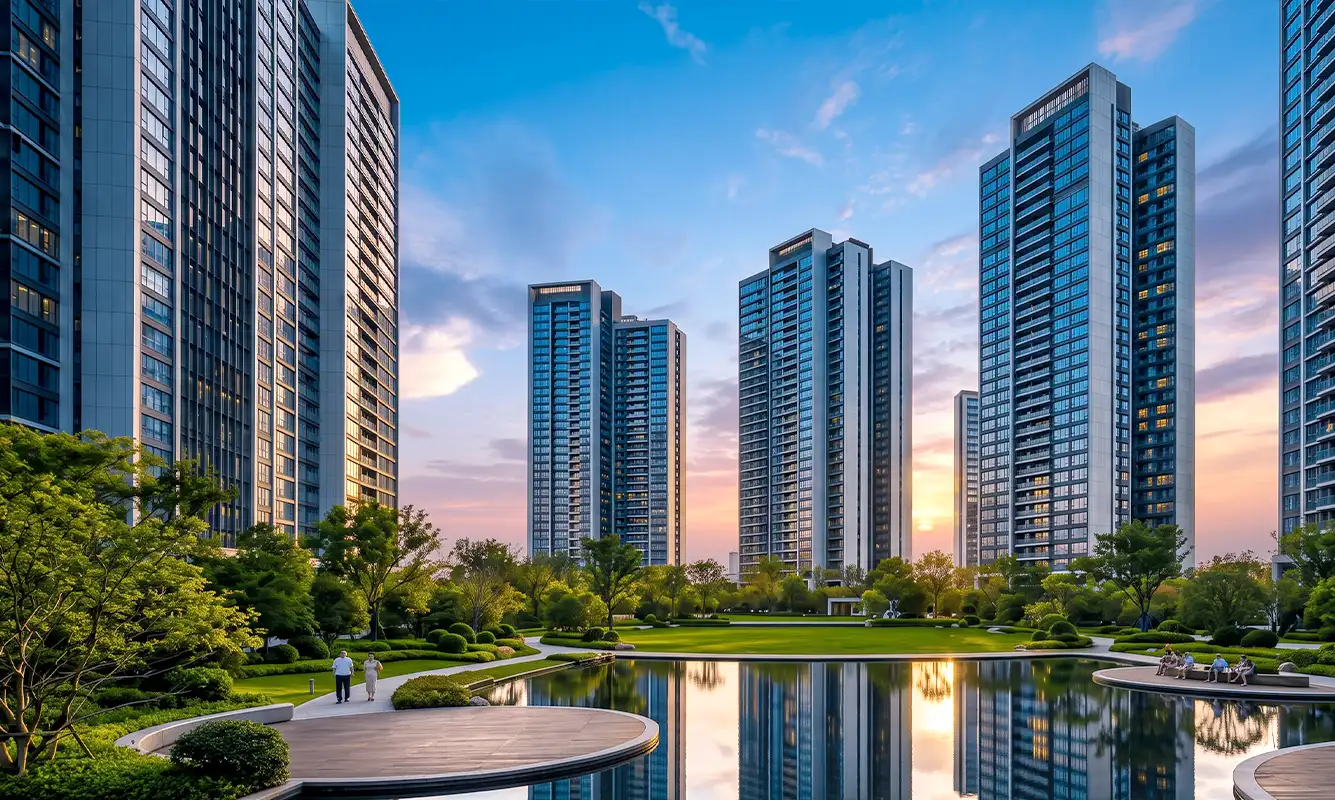
- Low-density living: just 9 towers on 14.6 acres, with about 78% open, landscaped area.
- Privacy built in: homes planned with no shared walls.
- A 1 lakh sq. ft. clubhouse with pool, gym, yoga zone, indoor games and more.
- Large, practical layouts: 2,200 to 3,400 sq. ft., with servant, study and family lounge options.
- Well-connected Sector 90: links to the Dwarka Expressway, NH-48 and Pataudi Road; IGI Airport about 30 minutes away.
- Direct from the developer: deal straight with Pardos Real Estate, with a free guided site visit.
Frequently asked questions
Can I get a home loan for Pardos Sakura?
Banks and NBFCs generally fund under-construction projects once the project is on their approved panel and has the required approvals in place. Ask the Pardos sales team for the current list of lenders funding Pardos Sakura.
How much home loan can I get for a Pardos Sakura apartment?
Lenders typically fund 75-90% of a property's value depending on the loan amount and the bank's policy, with the rest paid as your own contribution. Exact eligibility depends on your income, credit profile and the bank's current norms.
How does the EMI work during construction?
On a construction-linked plan, the bank usually disburses the loan in parts as each instalment falls due, and you pay pre-EMI (interest only) on the amount disbursed until the full loan is released, after which regular EMIs begin.
Get the Price List & Payment Plan
Share your details and the Pardos sales team will send you:
- Unit-wise price list and cost breakup
- Current payment plan document
- Free guided site visit slots
More Pardos Updates
Pardos Sakura Price List: Cost & Payment Plan
Pardos Sakura price list: unit-wise cost from ₹2.80 Cr, EOI amount, how the payment plan works and what decides the final price.
How to Book Pardos Sakura: EOI Process
How to book Pardos Sakura, Sector 90 Gurgaon in 5 steps: register, get the price sheet, visit the site, choose a unit and submit the ₹10 Lakh EOI.
Pardos Sakura Sector 90 Gurgaon: Complete Project Guide
Everything about Pardos Sakura, Sector 90 Gurgaon: 3 & 4 BHK sizes, 14.6-acre plan, amenities, location, price from ₹2.80 Cr, EOI and possession.